Skip to content

Mid-market ecommerce brand marketing agency

Marketing for mid-market ecommerce brands: margin by product, honest measurement, channel mix decisions and getting past the plateau after early growth.

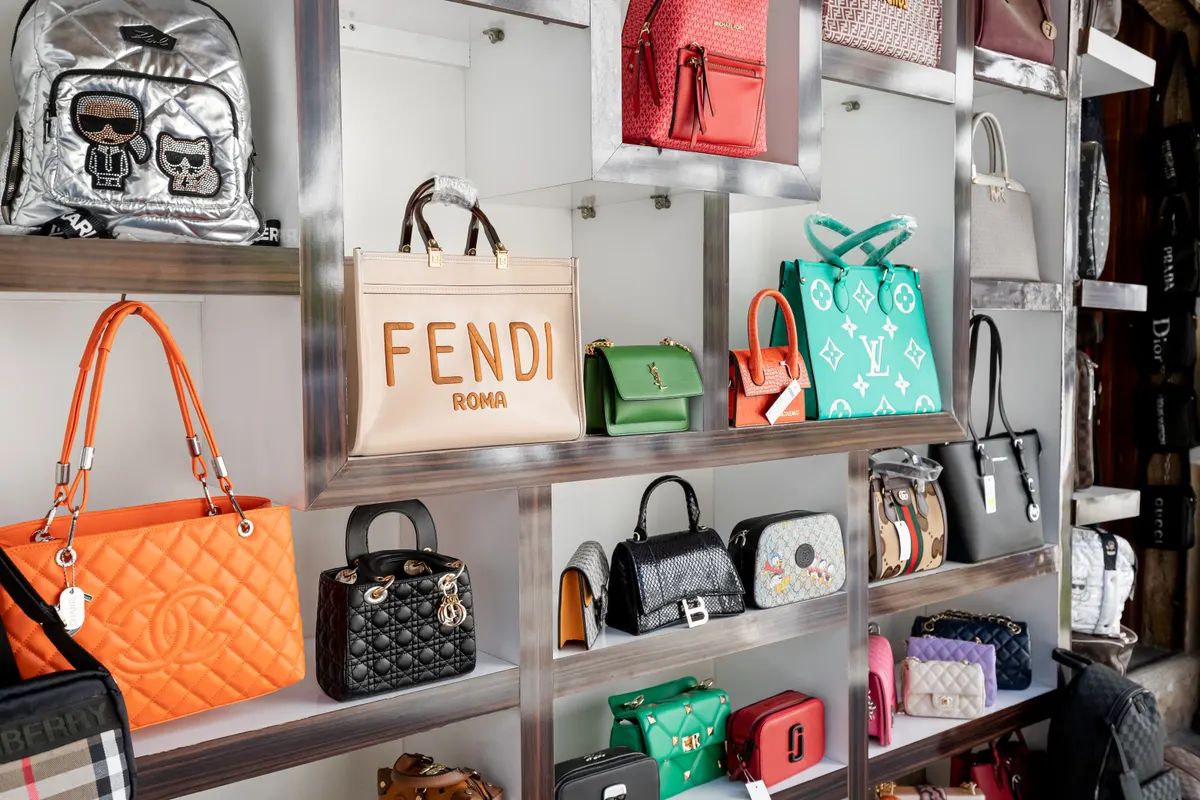
Mid-market ecommerce brand marketing agency: counterfeit fakes of bags of famous world brands of fashion accessories for sale at market - Gucci, Yves Saint Laurent, Chanel and others.

Why growth gets harder after the first stage

Mid-market brands usually arrive at the same point. The early growth came from one or two things working unusually well, the team was built around those things, and then the curve flattened. Spending more on the channel that got you here now costs more per order than it returns, the obvious efficiencies have been taken, and everyone is busy. The next stage is not another tactic. It is understanding which parts of the business actually make money and reallocating towards them.

We write growth plans for brands at that stage. The plan starts with margin by product and by channel, because most decisions at this size are made on revenue and revenue hides a great deal. It looks at how you measure, since a business spending seriously across several channels cannot run on platform reported numbers that each claim the same orders. And it looks at the constraints that are not marketing at all: cash tied up in stock, lead times, warehouse capacity and the number of people available to do the work.

Then it deals with the mix. Which channels are genuinely incremental, which are collecting demand you already created, which products should carry the budget, and what should be brought in house versus done by a partner. The output is a written plan with a monthly scope and a base fee plus growth share, not a percentage of what you spend.

In the early stage a brand grows by finding an audience that was not being served and reaching it cheaply. That works until the cheap reach runs out, which it always does. What remains is a larger, less interested audience who need more convincing and cost more to reach, and a set of existing customers who are being treated as though they were still strangers.

The customer has changed too. Early buyers came because the product was different. Later buyers are comparing options, reading reviews, waiting for a sale and taking longer to decide. The same ad that converted an enthusiast does not convert a considerer, and the same page that worked when your visitors were already convinced now leaves questions unanswered.

Internally the constraint moves. It stops being demand and becomes some combination of stock, cash, warehouse throughput and people. A campaign that could spend twice as much is limited by a product with a four month lead time, and nobody in the marketing meeting knows that until it sells out.

Measurement gets harder at exactly the moment it matters more. With several channels running, each platform claims credit for the same orders, and the brand ends up with a set of reports that add up to more revenue than the bank account shows. Decisions made on those numbers tend to overspend on channels that harvest demand and underspend on the ones that create it.
Where mid-market ecommerce brands
lose revenue

The four levers, in this niche.

Visitors

Visitors: separate the demand you create from the demand you collect

Brand search, direct traffic and returning customers are demand you already earned, and buying it again looks like efficient performance marketing while adding nothing. Prospecting is what grows the business and it always looks worse in a report. We split the two in measurement so the decision is made honestly, then test whether the harvesting channels are incremental by holding them back in a controlled way rather than by arguing about attribution models.

Conversion rate

Conversion: the same site is now serving a harder audience

Pages built for early enthusiasts stop working on a considered buyer. That audience wants sizing detail, delivery certainty, comparison between your own options, reviews that address their specific doubt and a returns policy that reduces the risk of being wrong. At this scale there is enough traffic to test properly, so changes are validated rather than argued about, and the tests are run on the pages and steps that carry the most revenue rather than on whatever was easiest to change.

Average order

Order value: know which products are worth selling

Gross margin varies enormously across a mid sized catalogue and most brands do not have it in front of them when they set budgets. Once it is visible the decisions get easier: promote the products that fund growth, bundle the ones with room, rationalise the tail that consumes attention and warehouse space without earning either, and set thresholds and offers against real margin rather than a blanket percentage that quietly loses money on half the range.

Repeat purchases

Repeat purchases: the cheapest growth left in the business

By this stage a brand has a large customer file and usually underuses it. Repeat rate by cohort, by first product bought and by acquisition channel tells you which customers are worth acquiring more of, which is a better use of that data than another newsletter. Then the programme is built on real intervals rather than a calendar. For most brands at this size, a percentage point on repeat rate is worth more than the same effort spent on lowering cost per acquisition.

What we do for
mid-market ecommerce brands

Five channels, one plan.

Google Shopping and search

Google Shopping and search ads at mid-market budgets

At this spend the account structure should follow the business rather than the platform's defaults. Products grouped by margin and by strategic priority, brand and non branded separated so that a strong blended figure cannot hide weak prospecting, and budgets set against what each product can actually afford.

Feed quality is still where the largest gains sit, because it affects every impression. Titles that match how shoppers search, complete attributes, correct variant grouping, and availability that reflects real stock.

The strategic question at this size is incrementality. Branded search and remarketing often show excellent returns while adding very little, and the only honest way to find out is a controlled test rather than a debate about models. We run those tests in a way that is safe, measure at the level of total business performance rather than campaign level, and reallocate accordingly. Peak periods are planned in advance with budgets raised before demand rather than during it, since a campaign learning during your biggest week is a campaign wasting your biggest week.

Meta and TikTok

Meta and TikTok ads at mid-market budgets

Social is usually where the growth budget sits and where the measurement is hardest. Two things improve it more than tactical changes: better event data through server side tracking configured properly, and a creative pipeline that produces enough new concepts to keep prospecting working.

Creative is the main variable at this level. Not new cuts of the same footage but genuinely different reasons to care, tested against a threshold decided in advance. Most accounts we review are spending well and testing narrowly.

Audience work is about exclusions as much as targeting. Recent customers, subscribers and people who bought the exact product should not be paid for again, and the segments that define them should come from your own order data. For measurement, geographic holdout tests give a more honest read on incremental contribution than platform reporting, and at mid-market budgets there is enough spend for those tests to produce a usable answer within a reasonable period.

Merchant Center and the feed

Merchant Center and feed operations

Feed work stops being a project and becomes an operation with someone accountable for it. Rules generate titles from product fields, supplemental feeds carry attributes the product data does not hold, and automated exclusions remove products that are out of stock, unprofitable or being discontinued.

Margin data belongs in the feed as a custom label so campaigns can be built around what each product actually earns rather than around merchandising categories. Sell through and stock cover work the same way, which lets you stop advertising something that is about to run out and push something that has too much cover.

Monitoring matters because at this catalogue size a broken rule can quietly remove hundreds of products from advertising, and the revenue effect shows up before anyone notices the cause. Account health, disapprovals and price mismatches are checked on a schedule rather than when something looks wrong. Where the brand sells in several countries or through several storefronts, each gets its own configuration so prices and delivery estimates match the page the shopper lands on.

SEO and AI search

SEO and AI search for an established mid-market brand

A brand at this size has assets a smaller one does not: authority, real customer questions, support data, review volume and enough product range to build genuine buying guides. The mistake is spending that on a blog that serves no commercial purpose.

The work that pays is on the pages closest to a purchase. Collection pages with proper introductions and internal linking, product pages with complete structured data and the specification a considered buyer needs, and guides that help someone choose between your own options. Those guides are also what an assistant quotes when someone asks how to pick within your category.

Technical control matters as the catalogue grows, since filters and tag pages generate large numbers of near duplicate URLs that dilute the site. Site speed is worth auditing because app and script accumulation is nearly universal at this stage. And the questions your support team answers most often should be published as pages, because they are proof of what real customers actually want to know before they buy.

Email and SMS

Email, SMS and the customer file

The customer file is the most undervalued asset in a mid-market brand. Segmented by product bought, order frequency, value and acquisition channel, it tells you where to spend on acquisition as well as what to send.

The programme is built from behaviour rather than a calendar. Replenishment timed to each product's real interval, a first to second order sequence aimed at the moment most customers are lost, a high value track that offers access rather than deeper discounts, and a lapsed sequence timed to each customer's own rhythm.

At this size the operational flows are worth as much as the promotional ones. Tracking updates, care and usage content, and answers to the questions that generate support tickets all reduce cost while improving retention. Campaign sends are planned against the same margin data that drives advertising, so a promotion is not quietly built on the products that can least afford it. SMS is used for time sensitive moments and kept scarce, since a mid-market list is an asset that takes years to rebuild if it is worn out.

First three fixes

What the plan usually starts with for mid-market ecommerce brands.

  1. Budgets set on revenue rather than margin

    Nobody in the marketing meeting has gross margin by product in front of them, so spend follows whatever sells rather than whatever earns. We build a view of margin by product and by channel, put it into the feed as labels, and set targets per group so the budget stops being decided by the products that are simply easiest to sell.

  2. Platform reports that add up to more revenue than the bank

    Each channel claims the same orders and the total exceeds actual sales, so decisions get made on numbers nobody quite believes. We set up measurement based on your own order data, use blended figures to judge whether spending more is working, and run controlled tests to find out which channels are genuinely adding sales.

  3. Marketing plans that ignore stock and lead time

    A campaign scales into a product with months of lead time and no cover, or pushes hard on a line the warehouse is trying to clear. We connect the media plan to stock cover and lead times, agree rules for what happens when cover runs short, and put the products with too much cover in front of the budget instead.

Questions from mid-market ecommerce brands

It is expected rather than normal, and it is why growth planning has to work in totals rather than in channel level ratios. Early spend reaches the most interested people, and each additional pound reaches someone slightly less interested. The useful questions become how much profit each additional amount of spend adds, and whether the same money would do more in order value or repeat purchase work, which carry no media cost.

Usually both, split by what benefits from continuity and what benefits from range. Brand knowledge, merchandising, creative direction and customer understanding sit best in house. Channel execution, feed operations and measurement work well with a partner who sees many accounts. The decision that matters more is who owns the plan, because a team of specialists with no shared plan produces activity rather than growth.

Test it rather than argue about it. Reduce or pause branded activity in a controlled way, in some regions and not others or for a defined period, and measure total revenue rather than campaign revenue. Sometimes most of it would have arrived anyway; sometimes competitors are taking a real share. It differs by category and by how much your name is being bid on, which is why the answer has to be measured in your own business.

It means our income does not rise when your spend does. A percentage of spend rewards recommending a bigger budget; a base fee plus growth share scoped in the plan does not. It also makes the work easier to plan, because we can spend time on feed quality, measurement, order value and retention work that has nothing to do with media spend but usually moves profit more than the media does.

In the three places that do not require reaching new people. Margin, by understanding which products earn and moving budget and merchandising towards them. Order value, through bundles, thresholds and the accessories your customers already buy elsewhere. And repeat rate, which for most brands at this size is the largest single opportunity in the business and the one with the least competition for attention internally.

Other marketplace & multi-channel sellers stores we work with

Send your mid-market ecommerce brand store.

The plan says which lever is leaking and what to fix first, for your store as it is today.

Store, name, email and phone. A person replies from a real inbox. Privacy

Get your free growth plan